
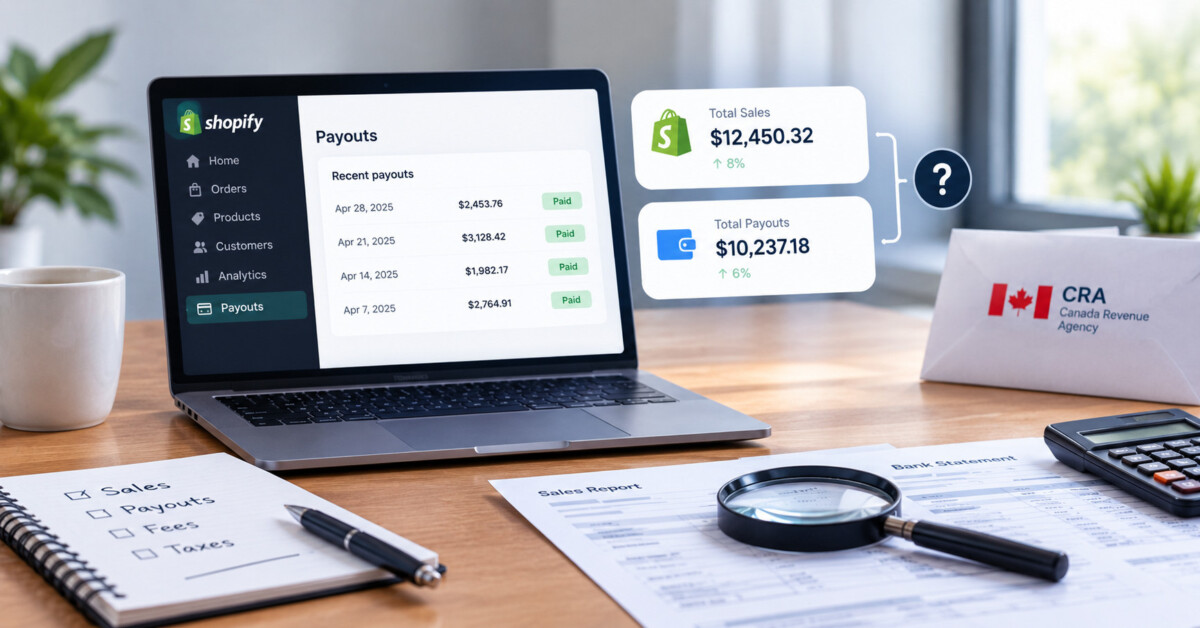
Your Shopify sales report and your bank deposits will never match, because payouts arrive net of fees, refunds and reserves. For Canadian sellers, that ordinary gap is what a CRA reviewer sees first, and reconciling it monthly is what makes an audit cheap.
The gap between what your store sold and what your bank received is not an accounting error. It is the normal behaviour of your payment processor, and it is the first thing anyone reviewing your file will ask you to explain.
A store does $40,000 in a month. The owner looks at the Shopify dashboard, sees $40,000, and writes $40,000 in the revenue column. The bank received closer to $36,000. Nobody stole anything. Nothing broke. That four thousand dollar difference is just what happens when gross order value meets a payment processor, and it repeats every month, quietly, for years.
Most of the time this costs nothing. It costs something on the day a letter arrives asking you to explain why your reported revenue does not tie to your deposits. At that point the question is not whether you were honest. It is whether you can demonstrate it, quickly, with documents you already have. Those are two very different problems, and only one of them is solved by knowing your numbers are right.
This piece is written for Canadian operators specifically, because the thresholds, the retention rules and the agency involved are Canadian. The reconciliation discipline underneath it is universal. If you sell into the United States or the United Kingdom, the mechanics of the gap are identical and only the rulebook changes.
A Shopify payout is never the same number as the orders behind it, because four things come out before the money moves: processing fees, refunds issued since the last payout, chargebacks, and any reserve held against future disputes. The dashboard reports what customers agreed to pay. The bank reports what survived the trip.
Refunds are the deduction that confuses people most, because they travel backwards in time. Shopify’s own documentation is explicit that when you refund a customer, the refunded amount is deducted from your next available payout. A November order refunded in January reduces a January deposit. If you are reconciling by matching deposits to the orders placed in the same week, that refund will look like money that went missing.
Timing does the rest. Settlement periods vary by region, and on top of that Shopify notes that after funds are paid out they might take an additional one to three days to display in your bank account, with weekends and holidays not counting toward settlement. The practical result is that the last several days of every month’s orders land in the following month’s deposits. Your revenue month and your cash month are not the same month, and they never were.
Illustrative benchmark, using a representative card rate rather than your actual plan pricing: 500 orders at an average of $80 gives you $40,000 in gross sales. Processing at 2.9 percent plus 30 cents takes about $1,310. A 6 percent refund rate takes another $2,400. You are already down to roughly $36,290 before the timing shift moves the final week’s orders into next month. That is a gap of about nine percent, produced by nothing but normal operations.
You stop being a small supplier the moment your taxable revenue exceeds $30,000, and the CRA measures that two ways: within a single calendar quarter, or across four consecutive calendar quarters. The distinction matters more than most operators realise. Under the CRA’s registration rules, if you cross the line inside one quarter you must start charging GST/HST on the supply that made you exceed $30,000. Not the next order. That one.
For a store growing normally, this is a threshold you cross on an ordinary Tuesday during a good week, with no notification from any system you use. Shopify will not tell you. Your bank will not tell you. The obligation begins whether or not anyone noticed, and the tax you failed to collect on subsequent sales does not disappear; it becomes something you owe out of margin you already spent.
This is where a lot of merchants discover the difference between tax calculation and tax compliance. Shopify will compute rates and apply them at checkout once configured, but as we have covered before, Shopify calculates some taxes and leaves the filing entirely to you. The platform is a calculator, not a filing agent, and it has no view into revenue you earn through channels it cannot see.
Stage guidance, because this lands differently depending on where you are. Under $50K in annual revenue, the job is simply to watch the rolling four quarter figure and know your registration date in advance. Between $500K and $2M, registration is long behind you and the real exposure is provincial: where you have customers, which rate applied, and whether the tax you collected matches the tax you remitted, quarter by quarter. Above $2M, this is a controls question rather than a knowledge question, and it belongs to somebody whose job it is.
The CRA completed 84,356 compliance cases with $18.1 billion in fiscal impact in 2024 to 2025, but that figure is not your audit probability, and anyone quoting it at you as though it were is either careless or selling something. In the CRA’s 2024 to 2025 Departmental Results Report, that number sits under the agency’s objective to combat the most sophisticated and complex cases of aggressive tax planning, evasion and fraud.
That is a specific population, and a small Shopify store with clean books is not the profile it describes. Fiscal impact is also not cash collected; it is the assessed value of the adjustments, before objections, appeals and write offs. Two large numbers sitting next to each other do not describe the risk facing an ordinary DTC brand in Langley or Mississauga.
The honest version is less dramatic and more useful. Most ecommerce operators will never see a full audit. A meaningful number will receive a request for supporting documents, a pre assessment review, or a notice of reassessment, and those are different processes with different scopes. Reading the letter carefully and answering what it actually asks is most of the work.
Apply the eighteen month test here, the same one worth applying to any tactic. Fear of an audit will not still be motivating you in eighteen months. A monthly close that takes ninety minutes will still be running, and it will have paid for itself in margin visibility long before anyone from the government reads a word of it. Build the system for the ordinary reason, and let the audit protection be the side effect.
You are generally required to keep your records for a minimum of six years from the end of the last tax year to which they relate, which means the reconciliation you skip this month is one you will still owe in 2032. The CRA’s guidance on business records defines a record broadly enough to cover essentially every artifact your stack produces, and asks only that computerized records be clear and easy to read.
That last phrase is doing more work than it appears to. A CSV export from an app you stopped paying for in 2027 is not clear and easy to read in 2032. Neither is a payout report from a processor you migrated away from. The retention obligation sits with you, not with your vendors, and your vendors will not hold the data for six years on your behalf.
The practical move is to decide, once, which system is the authoritative record for each figure you report, and then export from it on a schedule. The mapping below is the version that holds up for a typical Shopify stack.
If you are early and doing this by hand, the habits are more important than the tooling, and the bookkeeping fundamentals worth building before revenue gets complicated will carry you further than any app will. Once payout volume makes manual matching tedious, A2X is the standard bridge, and our walkthrough of connecting Shopify to QuickBooks Online through A2X covers the setup that posts payouts as summarised journal entries rather than a wall of individual transactions.
A month end close that ties Shopify gross sales to bank deposits through a documented payout reconciliation is what converts an audit response from an excavation into an export. The work is not complicated. It is just work that nobody does until there is a reason, and by then it is six years of it at once.
The sequence is the same every month. Pull the payouts report for the period. Match each payout to the deposit line on the bank statement. Account for the difference between gross orders and net payout across the four deductions. Post the fees, refunds and chargebacks to their own accounts rather than netting them into revenue, because a reviewer asking about your fee deduction wants to see fees, not a smaller revenue number. Then write one sentence explaining any timing difference at the period boundary, and save it with the export.
That last step is the one almost everyone skips, and it is the cheapest insurance in the routine. A short written note beside each month’s reconciliation, written while you still remember what happened, is worth more under review than a perfect spreadsheet with no explanation attached. It is also what lets somebody else pick up your file without interviewing you.
None of this is jurisdiction specific, which is the giveaway that it is a real operating discipline rather than a tax chore. The same payout gap and the same close routine show up for British sellers, where the Shopify accounting and VAT rules run on a £90,000 threshold and Making Tax Digital dictates the format. Different rulebook, identical reconciliation.
Bring in a specialist when the question stops being bookkeeping and starts being interpretation. Reconciling a payout is arithmetic. Explaining a shareholder loan, defending how a transaction was characterised, or handling several open years at once is judgment, and it is judgment with money attached to being wrong.
The specific triggers worth watching for: more than one tax year under review at the same time, personal and business transactions running through the same account, shareholder accounts that need explaining, inventory valuation that has never been formally set, or a genuine disagreement with the agency about how something should be treated. Any one of those is a reasonable moment to stop optimising your own spreadsheet.
There is more than one honest answer about who to call, and the right one depends on what kind of problem you have. If the issue is that your books are behind, that is a bookkeeping engagement, and an ecommerce specialist who already understands multichannel payouts will be faster than a generalist; our review of EcomBalance covers what that service looks like and what it costs for brands at the seven and eight figure stage. If the issue is an active review or a reassessment you intend to dispute, that is representation rather than bookkeeping, and firms that specialise in it, such as Faris CPA, publish their approach to CRA tax audit help for businesses working through that process. If the disagreement has become genuinely adversarial, a tax lawyer rather than an accountant is the conversation, and any competent advisor will tell you that themselves.
What does not change with any of them is where responsibility sits. The taxpayer remains accountable for the accuracy of what is filed, regardless of who assembled it. Hiring well buys you speed, experience and somebody to handle the correspondence. It does not transfer the obligation, and any advisor who implies otherwise has told you something useful about themselves.
Your payouts are smaller than your sales because four things are deducted before the money reaches your bank: payment processing fees, refunds issued since your last payout, chargebacks, and any reserve held against future disputes. Shopify’s documentation confirms that a refunded amount is deducted from your next available payout, which is why a refund on an old order reduces a current deposit. On top of the deductions, settlement takes a few business days and banks add another one to three days on their end, so the final days of each month’s orders arrive in the following month’s deposits. The gap is normal. Not being able to explain the gap is the problem.
You must register once your taxable revenue exceeds $30,000, measured either within a single calendar quarter or across four consecutive calendar quarters. If you cross the threshold inside one quarter, the CRA requires you to start charging GST/HST on the very supply that took you past $30,000, not on the next order. If you cross it across four quarters without exceeding it in any single one, you stop being a small supplier at the end of the month following that quarter, and charge from your effective registration date. No system in your stack will alert you when this happens, so track the rolling figure yourself and know your likely registration date before you reach it.
You are generally required to keep records for a minimum of six years from the end of the last tax year to which they relate, and longer in certain circumstances. The CRA defines a record broadly, covering invoices, statements, agreements, charts and any other proof containing information, in writing or any other form. Computerized records are acceptable provided they are clear and easy to read. The practical risk for ecommerce operators is vendor churn: a payout report from a processor you left, or an export from an app you cancelled, is not something that vendor will retrieve for you in year five. Export on a schedule and store the files somewhere you control.
Expect requests for filed returns, general ledgers, bank statements, sales invoices, expense receipts, payroll records and any relevant contracts for the periods under review. For an online store, the reconciliation between platform sales and bank deposits is usually the centre of the request, because that is where the apparent discrepancy lives. Have your Shopify orders export, your payouts report and your bank statements able to tie to each other, with fees, refunds and chargebacks posted to their own accounts rather than netted into revenue. Tax reports by province should reconcile to what you actually remitted. Organise the response in the same order the request was written.
Handle it yourself when it is a single straightforward document request and your records are complete and reconciled. Bring in help when complexity appears: multiple years open at once, personal and business money mixed in one account, shareholder accounts requiring explanation, inventory valuation that was never formally set, or a real disagreement about how a transaction should be treated. Match the professional to the problem. Books behind means a bookkeeping engagement, ideally with someone who already knows multichannel payouts. An active review or a reassessment you plan to dispute means representation. Genuinely adversarial means a tax lawyer. In every case, responsibility for accuracy stays with you.